Mathew Mattam
The message arrives in your email: “Congratulations! Your salary has been revised.” An additional ₹3,000 or ₹5,000 a month, perhaps accompanied by a new designation. You immediately begin making plans. A better phone, a new vehicle, a larger house or an additional loan suddenly appears affordable. For a few days, the future looks more secure. But then comes a hospital bill, an urgent home repair, a delayed salary or an unexpected job loss—and that feeling of security disappears.
This is the uncomfortable truth many working families experience. A salary hike can increase income, but it does not automatically create financial stability. If a higher salary alone guaranteed security, families with two earning members would never struggle to manage an emergency. Employees receiving regular increments would not remain trapped in credit-card debt and expensive personal loans. People earning ₹50,000 a month would not have to borrow when faced with one unexpected medical expense.
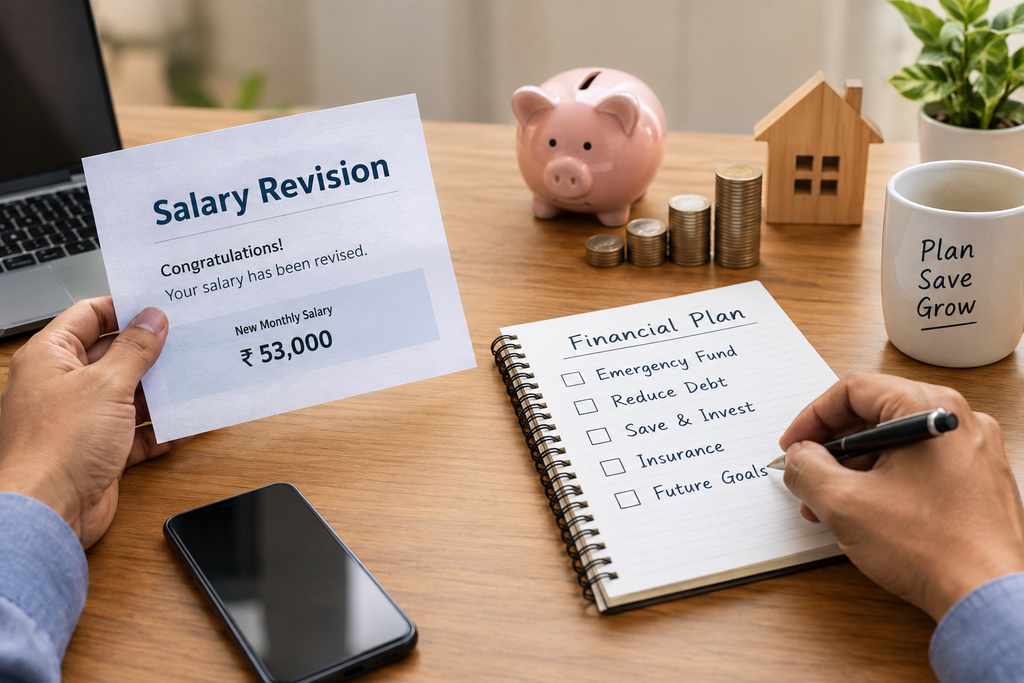
The problem is not always how little we earn. Often, it is how little control we have over what we earn. As income rises, expenditure frequently rises with it. We upgrade our lifestyle before strengthening our financial foundation. A salary increase becomes a larger EMI, a more expensive school, another subscription or an impulsive purchase. More money enters the household, but very little remains. Income has increased, yet financial anxiety continues.
Imagine two colleagues. One earns ₹25,000 a month but has no emergency savings, no insurance and several loan instalments. The other earns ₹15,000, tracks every expense, avoids unnecessary debt and has saved enough to manage the household for two months. Who is financially more stable? The answer is not necessarily the person with the higher salary. Stability belongs to the person who has greater control over income, expenditure, savings and risk.
Financial freedom, therefore, does not begin with earning more. It begins with understanding money. This is financial literacy—the ability to distinguish between needs and wants, separate household and business finances, understand assets and liabilities, recognise good and bad debt, calculate the actual cost of borrowing and appreciate the importance of a good credit record. A salary hike teaches none of these things. Without this knowledge, a higher income can simply create larger financial mistakes.
A salary hike without financial literacy is like pouring more water into a leaking bucket. The bucket appears fuller for a while, but the water continues to escape. Financial planning first identifies and closes the leaks. It helps us understand where our money goes, why we repeatedly run short and what changes are required. Tracking daily expenditure, preparing a household budget and setting limits for unnecessary spending may appear simple, but these habits are the beginning of financial control.
Understanding money, however, is only the first step. The next step is financial capability—the confidence and practical ability to manage it. A financially capable person can use banking and UPI services safely, identify OTP fraud and fake loan applications, compare interest rates, maintain financial records and prepare a realistic debt-repayment plan. Such a person can approach a bank confidently, understand the documents required and select a suitable financial product instead of depending blindly on agents or informal lenders.
Consider another example. One employee receives an ₹8,000 salary increase and immediately takes a personal loan carrying a high interest rate. Much of the new income is consumed by the EMI. Another employee receives no hike but begins saving ₹50 a day. That small habit creates approximately ₹18,000 in a year. If the second employee also maintains proper records and develops a viable business idea, those savings may help create an additional source of income. One person received more money; the other built greater control.
The next stage is financial security—the ability to protect one’s household from financial shocks. Security is not a vague hope that next year’s increment will solve everything. It is built through measurable goals. Instead of saying, “I want to save more,” a person decides, “I will save ₹30,000 within 12 months for my daughter’s education.” A clear goal changes behaviour because it provides an amount, a purpose and a deadline.
Inflation makes planning even more important. A 7% salary hike may look attractive, but if living costs rise by 6%, the actual improvement in purchasing power is very small. Money kept without an appropriate plan may gradually lose value. This does not mean everyone should rush into shares, property, gold or mutual funds. Each option carries a different level of risk, return and liquidity. Investment should follow a person’s goals, responsibilities and ability to bear risk—not rumours, advertisements or social-media advice.
Financial freedom is reached when a person can reduce expensive debt, build productive assets, protect the family and make independent financial choices. It does not necessarily mean becoming extremely wealthy or retiring at forty. For an ordinary household, it may mean being able to manage six months without a salary, pay a medical bill without borrowing, educate children without selling assets and live after retirement without depending entirely on others.
The most important financial question is therefore not, “How much do I earn?” It is, “If my income stopped tomorrow, how long could my family manage without borrowing?” The answer reveals our real level of stability. A person with a 30% salary hike but no savings, insurance or debt plan may be less secure than someone with a modest income and disciplined financial habits.
After your next salary increase, ask yourself five questions: Has my emergency fund increased? Has my costly debt reduced? Have I started saving or investing for a specific goal? Is my family better protected through insurance, pension planning and updated nominations? Have I begun developing another source of income? If the answer is “no” to most of these questions, you have received more money—but not greater stability.
A salary hike changes the figure on a payslip. Financial literacy changes understanding. Financial capability changes behaviour. Financial security builds resilience. Financial freedom expands choice. A higher salary may make today more comfortable, but only sound financial planning can make tomorrow more secure. Real career stability begins when we stop merely earning and spending—and start controlling, protecting and growing what we earn.

This Post Has 3 Comments
Very true,
Writgly said in the article….thanks Mr.Mathew….wonderfully put down the points.
Yes, Mathew,
Very well explained and presented in a very simple and easy-to-understand way. Financial Literacy, Financial Capability and Financial Security are indeed crucial aspects of achieving Financial Freedom.
I believe everyone should consciously practice these disciplines in life to move towards financial freedom. **More money without financial discipline and control can lead to disaster, whereas less money with greater control and discipline can still lead to financial freedom.**
A very insightful article. 👏
Good article